
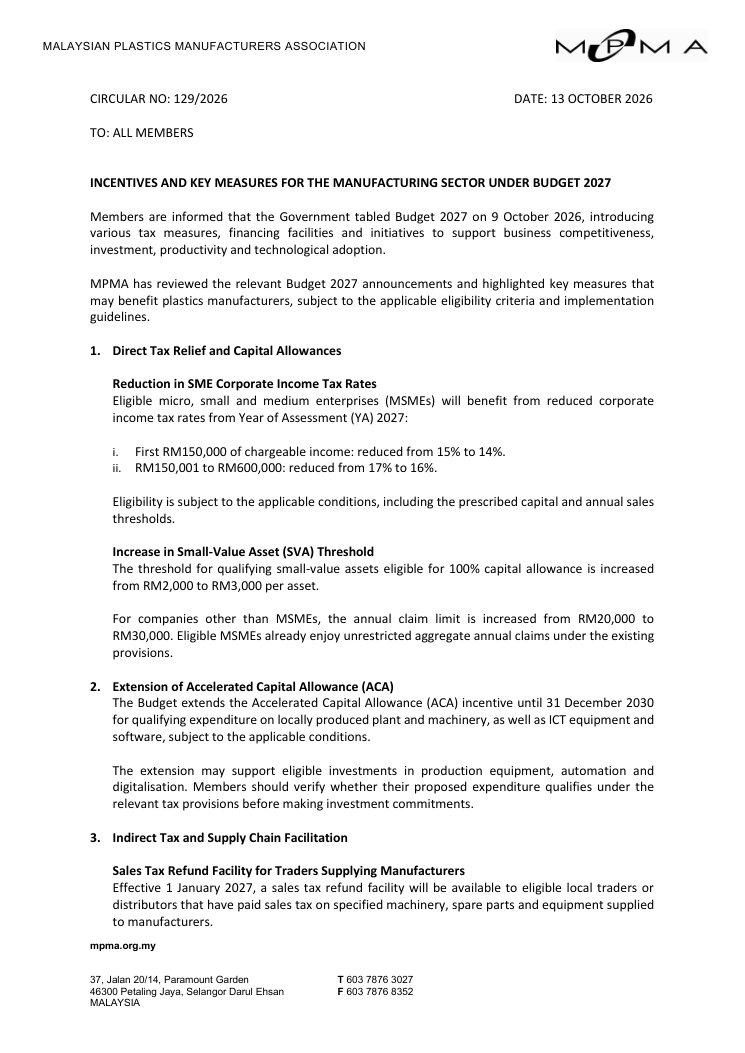
Members are informed that the Government tabled Budget 2027 on 9 October 2026, introducing various tax measures, financing facilities and initiatives to support business competitiveness, investment, productivity and technological adoption.
MPMA has reviewed the relevant Budget 2027 announcements and highlighted key measures that may benefit plastics manufacturers, subject to the applicable eligibility criteria and implementation guidelines.
Direct Tax Relief and Capital Allowances
Reduction in SME Corporate Income Tax Rates
Eligible micro, small and medium enterprises (MSMEs) will benefit from reduced corporate income tax rates from Year of Assessment (YA) 2027:
i. First RM150,000 of chargeable income: reduced from 15% to 14%.
ii. RM150,001 to RM600,000: reduced from 17% to 16%.
Eligibility is subject to the applicable conditions, including the prescribed capital and annual sales thresholds.
Increase in Small-Value Asset (SVA) Threshold
The threshold for qualifying small-value assets eligible for 100% capital allowance is increased from RM2,000 to RM3,000 per asset.
For companies other than MSMEs, the annual claim limit is increased from RM20,000 to RM30,000. Eligible MSMEs already enjoy unrestricted aggregate annual claims under the existing provisions.
Extension of Accelerated Capital Allowance (ACA)
The Budget extends the Accelerated Capital Allowance (ACA) incentive until 31 December 2030 for qualifying expenditure on locally produced plant and machinery, as well as ICT equipment and software, subject to the applicable conditions.
The extension may support eligible investments in production equipment, automation and digitalisation. Members should verify whether their proposed expenditure qualifies under the relevant tax provisions before making investment commitments.
Indirect Tax and Supply Chain Facilitation
Sales Tax Refund Facility for Traders Supplying Manufacturers
Effective 1 January 2027, a sales tax refund facility will be available to eligible local traders or distributors that have paid sales tax on specified machinery, spare parts and equipment supplied to manufacturers.
The facility also covers specified inputs used in the manufacture of pharmaceutical products, animal feed, fertilisers and pesticides, subject to the applicable conditions.
Members should note that the announced facility applies to the specified goods and is not a general sales tax refund for all manufacturing inputs. Ordinary plastic resin and other plastics raw materials are not expressly identified in the Budget announcement; members should confirm their eligibility under the implementing rules.
Industrial Growth, Strategic Funds and Special Economic Zones
Strategic Growth Funds
A combined RM2.1 billion is made available through the New Industrial Master Plan (NIMP) Fund, Kumpulan Wang Persaraan (KWAP) Pemacu Fund and Khazanah Malaysia's Mid-Tier Companies (MTC) Fund, to strengthen mid-tier companies in strategic sectors, including electrical and electronics, digital technology, aerospace and medical devices.
Plastics manufacturers supplying these sectors may explore potential opportunities, subject to the respective funds' investment mandates and eligibility requirements.
Johor-Singapore Special Economic Zone (JS-SEZ)
The JS-SEZ Masterplan and Blueprint are scheduled for launch by the end of 2026. Industrial development initiatives include Nexus Sedenak and efforts to strengthen strategic supply chains.
Special Border Economic Zones (SBEZ)
The Government is strengthening eight northern border economic zones. This includes the proposed development of the 122-acre NCT InnoSphere heavy vehicle, engineering, maintenance and logistics hub, complementing industrial activities in Kulim and Penang. (Note: NCT refers to NCT Group of Compnaies)
These developments may create indirect opportunities for plastics manufacturers through industrial expansion, supply-chain participation and logistics development.
Financing Facilities and Export Support
Financing Guarantees through Syarikat Jaminan Pembiayaan Perniagaan (SJPP) Berhad and Credit Guarantee Corporation (CGC) Malaysia Berhad
SJPP and CGC will provide financing guarantees of up to RM32 billion. The guarantee scope is expanded to cover mid-tier companies across sectors, with the individual guarantee limit increased to RM50 million. A further RM1 billion is earmarked to support qualifying corporate expansion through mergers and acquisitions.
Guarantees facilitate access to financing but are not direct grants or automatic loan approvals. Members should check the applicable scheme conditions.
Bank Negara Malaysia (BNM) and Bank Pembangunan Malaysia Berhad (BPMB) Financing
BNM will expand financing support for SMEs affected by the West Asia conflict to RM10 billion, comprising the existing RM5 billion facility and a further RM5 billion. Access remains subject to the applicable eligibility criteria and participating financial institutions' approval processes.
BPMB will allocate RM7 billion across strategic sectors, with a further RM1 billion to support local MSMEs expanding into export markets.
All financing remains subject to the relevant institutions' eligibility requirements and approval processes.
Export Promotion
The Malaysia External Trade Development Corporation (MATRADE) is allocated RM60 million to strengthen local exporters' capacity to diversify into overseas markets. Plastics manufacturers seeking to expand export sales should monitor MATRADE's programmes and application guidelines.
Stamp Duty Concessions
From 1 January 2027 to 31 December 2030, qualifying loan or financing agreements executed through peer-to-peer (P2P) financing platforms will be eligible for stamp duty remission, resulting in a nominal RM10 stamp duty, subject to the prescribed conditions.
A separate RM10 stamp duty remission applies to qualifying second-tier loan agreements involving mid-tier companies under specified supplier-financing arrangements. This does not mean that all loan agreements or all agreements involving excess credit facilities qualify.
Members should refer to the detailed requirements in the relevant Ministry of Finance (MOF) tax measures (Appendices 18–20 of the MOF Tax Measures document @ belanjawan.mof.gov.my) before entering into financing arrangements.
Automation, Digitalisation and AI Adoption
Malaysia Digital Economy Corporation (MDEC) AI and Automation Support Programme
An allocation of RM30 million is provided through the MDEC to support 4,000 MSMEs in adopting artificial intelligence (AI) and automation. The Budget also provides for training and certification of 5,000 AI professionals.
This initiative may offer opportunities for plastics manufacturers seeking to improve production efficiency, quality control, inventory management and other business processes.
The allocation should not be interpreted as an automatic grant entitlement. Members should await the detailed programme guidelines to confirm the form of assistance, eligibility criteria and application procedures.
Recommended Action for Members
Members planning capital expenditure, automation, digitalisation or export expansion are encouraged to:
i. Review their eligibility for the revised MSME tax rates and capital allowances.
- ii. Assess qualifying machinery and technology investments against the applicable tax incentive conditions.
- iii. Explore relevant financing and export support programmes through BNM, BPMB, SJPP, CGC and MATRADE.
- iv. Monitor the detailed requirements for the sales tax refund facility and stamp duty concessions.
- v. Follow MDEC announcements on AI and automation support.
- vi. Members should verify the applicable requirements with the Inland Revenue Board of Malaysia (LHDN), Malaysian Investment Development Authority (MIDA), MATRADE, BNM, BPMB, SJPP, CGC or other relevant agencies before making investment or financing commitments.
MPMA will continue to monitor developments and share relevant updates as further implementation guidelines become available.
Note: All measures outlined in this circular are subject to the relevant legislation, official guidelines, eligibility requirements and approval by the respective authorities
 Signed circular (PDF)4 pages · opens in a new tabOpen PDF